
I've been warning people about independent, third-party automobile leasing companies for years. In fact, I wrote an article about them back in 2021 after a caller to my radio show told me he was planning to lease a new Ford F-150 through one of these companies. I explained why I thought it was a bad idea, and I've continued to give people that same advice ever since.
Well, this past Saturday, I got a phone call that illustrates my concerns better than anything I could have dreamed up. And when you see the numbers, I think you'll understand why I feel so strongly about this subject.
The caller told me that he and his family had leased more than 20 vehicles over the years through the same independent leasing company. Think about that for a minute. More than 20 vehicles! This wasn't somebody who had never leased before or was unfamiliar with the process. This was a longtime, loyal customer who apparently had been perfectly comfortable doing business with the same company for years.
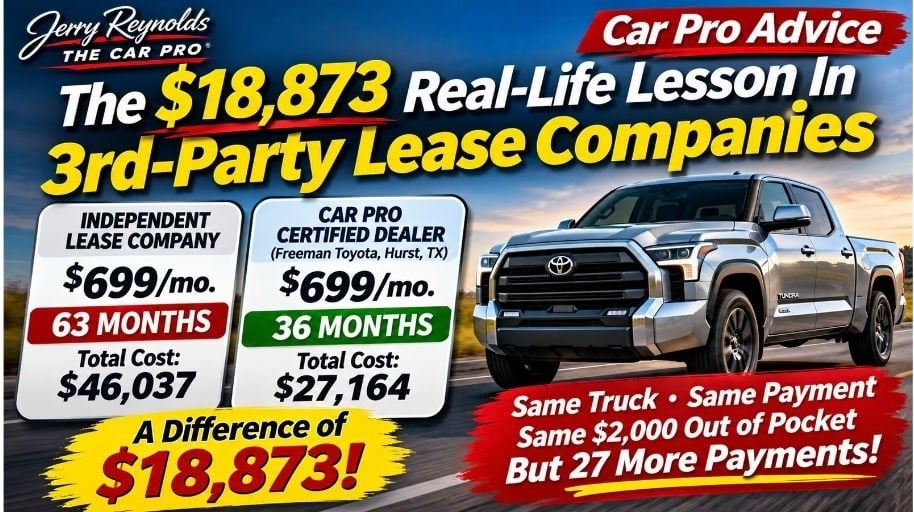
He was now interested in leasing a new 2026 Toyota Tundra, and his leasing company had given him a quote of $699 per month with $2,000 out of pocket. That sounds pretty attractive for a new full-size pickup, doesn't it?
There was just one little detail.
The lease was for 63 months.
That's five years and three months of payments on a vehicle he wouldn't own when the lease ended unless he exercised a purchase option, assuming his agreement provided one.
He decided to check with one of my Car Pro Certified Dealers. He asked for a lease quote on the same truck, with the same $2,000 out of pocket.
The dealer came back with a payment of $699 per month.
Exactly the same payment.
But here's the part that should get your attention: The Car Pro dealer's lease (Freeman Toyota in Hurst, TX) was for just 36 months!
Let me put those numbers into perspective.
The independent leasing company's proposal called for 63 payments of $699, totaling $44,037. Add the $2,000 out of pocket, and the total scheduled outlay was $46,037.
The Car Pro dealer's proposal called for 36 payments of $699, totaling $25,164. Add the same $2,000 out of pocket, and the total was $27,164.
That's a difference of $18,873 in scheduled payments!
Now, to be completely fair, the longer lease also provides 27 additional months of vehicle use, so this isn't a claim that two identical periods of transportation would differ in cost by $18,873. We would also need to compare mileage allowances, fees, residual values and other contract provisions before declaring the two leases identical in every respect.
But here's what we do know: This gentleman could drive the same new Tundra for three years at the same monthly payment and the same upfront cost, then be finished with his lease while the other arrangement would still have more than two years of payments remaining.
And that is precisely why I've been telling people to be extremely careful with independent leasing companies.
Let me explain how these operations generally work. Unlike an automobile manufacturer or a franchised dealership, an independent leasing company is essentially another party involved in arranging the transaction. It has to obtain the vehicle, ALWAYS through a dealership, arrange financing or funding, structure the lease and make enough money to operate its business.
There's nothing inherently illegal or dishonest about that. Some independent leasing companies provide excellent customer service, specialize in unusual vehicles or offer arrangements that make sense for particular customers. But their services don't eliminate the underlying cost of the vehicle, and adding another business to the transaction doesn't automatically make it less expensive.
In my experience, it can do exactly the opposite.
One of the biggest selling points these companies use is convenience. They'll tell you that you don't have to visit a dealership, negotiate with a salesperson or deal with the traditional buying process. They'll locate the vehicle, handle the paperwork and sometimes deliver it right to your home or office.
I understand why that appeals to people. Nobody wants to spend an entire day shopping for a vehicle if they don't have to.
But here's my question: How much are you willing to pay for convenience?
Today, many dealerships, including our Car Pro Certified Dealers, can handle much of the transaction remotely. You can discuss pricing, financing, lease terms and trade-in values without spending hours sitting in a showroom. Vehicle delivery may also be available. You don't necessarily need an independent leasing company to make the process convenient.
Another issue I've talked about for years is the way lease payments are advertised.
You'll see a beautiful luxury car or pickup advertised for a surprisingly low monthly payment. It looks terrific until you start reading the fine print and discover that the lease runs for 60 months or longer, requires a substantial amount of money upfront or allows very few miles per year.
A low monthly payment doesn't necessarily mean a good lease.
I have always liked leasing for the right customer, and one of the biggest advantages, in my opinion, is the ability to drive a new vehicle every few years without dealing with the long-term ownership concerns that come with keeping a vehicle for many years.
A 36-month lease often makes a lot of sense. Depending on the manufacturer and warranty, you may spend most or all of the lease term under the original factory warranty. You're driving a relatively new vehicle, and when the lease ends, you can evaluate your options and decide what to do next.
Stretch that lease to 60 or 63 months, and the equation changes.
You're now making payments on a vehicle that's four or five years old. Depending on the warranty and mileage, you may be responsible for repairs that wouldn't have been an issue during a shorter lease. Tires, brakes and other maintenance expenses can become more significant, and you may find yourself paying for repairs on a vehicle you're ultimately going to return.
Of course, a longer lease may be appropriate in certain circumstances, but I would never recommend one simply because somebody wants to advertise an attractive monthly payment.
There's another important consideration: mileage.
Most leases have mileage limits, and exceeding them can result in additional charges when the vehicle is returned. If you're comparing a 36-month lease with a 63-month lease, make sure you understand the annual mileage allowance and the total miles permitted under each agreement.
Don't just look at the payment. Look at the entire contract.
I also want consumers to understand residual values. That's the estimated value of the vehicle at the end of the lease, and it's an important part of calculating the payment. Some independent leasing companies advertise a guaranteed value at the end of the lease as though it's some extraordinary benefit they're providing.
But a predetermined residual value is a standard feature of many conventional automobile leases. The important questions are whether the lease is open-end or closed-end, what obligations you have at termination and whether you have a purchase option.
Those details matter a lot more than an advertising slogan.
One advantage of working directly with a franchised dealership is access to the manufacturer's financing programs. Automakers and their affiliated finance companies often offer special lease rates, residual-value support or lease incentives that can make a significant difference in the monthly payment and those are eligible to 3rd party lease companies, so the only way to be competitive is to stretch the lease, eliminating the reason to lease in the first place.
An independent leasing company may be able to arrange competitive financing through its own sources, but it doesn't have access to every manufacturer-sponsored lease program available through a participating franchised dealer.
That's why I always encourage people to compare.
And please don't assume that because you've done business with a company for years, you're automatically getting the best deal. Loyalty is a wonderful thing, and I believe businesses should reward it. But loyalty shouldn't replace doing your homework, especially when you're making a financial commitment that could last five years or longer.
That brings me back to Saturday's caller.
Here was a gentleman whose family had leased more than 20 vehicles through one company. I have no reason to believe he was unhappy with the service he'd received. But when he finally compared the lease quote with one from a Car Pro dealer, the difference was staggering.
Same truck. Same $699 monthly payment. Same $2,000 out of pocket.
One lease ended in 36 months. The other required 63 months.
If that doesn't demonstrate why you should shop with a Car Pro Certified Dealer, I don't know what does.
Before you sign a lease with anybody, I want you to get the complete terms in writing. Compare the selling price of the vehicle, money factor or rent charge, residual value, monthly payment, amount due at signing, mileage allowance, excess-mileage charges, disposition fees and early-termination provisions. Find out who the actual leasing company is and whether the agreement is open-end or closed-end.
And above all, multiply the monthly payment by the number of payments.
That simple calculation can be an eye-opener.
The Federal Trade Commission and the Consumer Financial Protection Bureau both encourage consumers to look beyond the monthly payment and understand the total financial obligations of a lease. It's good advice, and Saturday's caller is a perfect example of why it matters.
I'm not saying every independent leasing company offers a bad deal, and I'm certainly not suggesting every dealership offers a good one, I can only speak for the dealers on my radio show.
But I am saying that after decades in the automobile business, I remain convinced that most consumers should start with a reputable franchised dealership when considering a new-vehicle lease. Find a knowledgeable salesperson, ask about manufacturer lease programs and make sure you understand every part of the transaction.
If you still want to use an independent leasing company, that's your decision. Just give the dealership a chance to compete before you sign anything.
And if you've leased 20 vehicles from the same company without ever getting another quote, you might want to sit down before you see what you've potentially been missing.
As for Saturday's caller, I'm certainly glad he emailed me and picked up the phone and called the Car Pro Show. Lessons learned as I told him.
Because sometimes the most valuable thing I can do for a listener isn't to recommend a particular car, truck or SUV.
It's to help them recognize that a payment that looks good on paper may be hiding a deal that isn't nearly as good as it appears.
One last thing…when your vehicle breaks that you got from a 3rd party lease company, call them and see how they react. Oh wait, they don’t do service!
Remember, folks: When it comes to leasing, the monthly payment is only part of the story. The number of months matters just as much.